Download SATCO App
Track your portfolio on the go
 Bank Grade Security & Encryption
 Dedicated RM Support
 Industry Connect & Networking
 Regular Portfolio Monitoring
The people behind Satco Wealth.
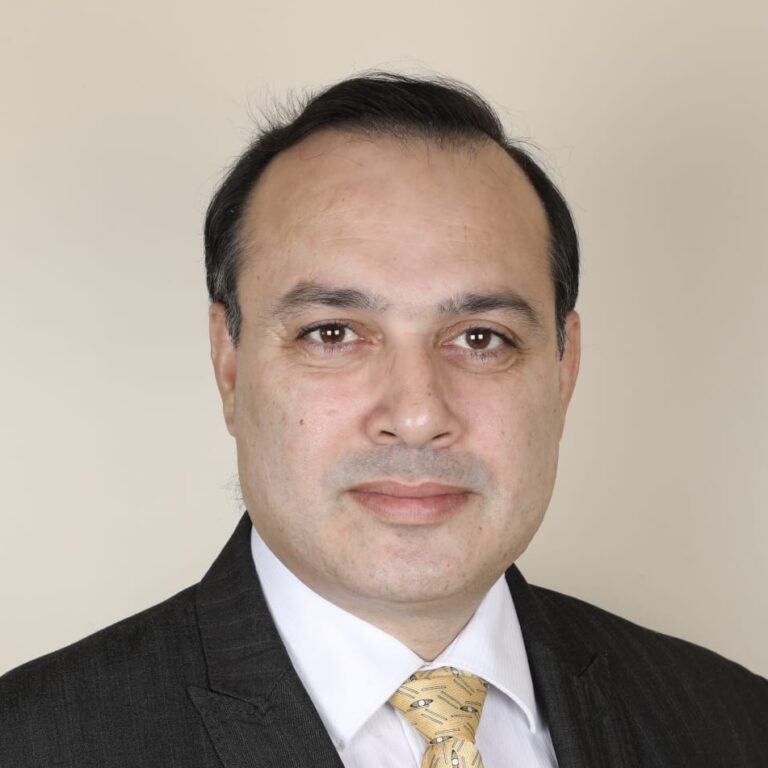 Mr. Deepak Jaggi
Deepak has over 30 years of experience in building retail businesses in financial services that has included his stint in Private Banking, Life Insurance, PMS and Mutual Funds. Worked in organizations like Kotak Securities, Zurich Mutual Fund, HDFC Life Insurance and Deutsche Mutual Fund. His last assignment was with PGIM Mutual Fund as an Executive Director and Head of Retail Sales pan India. He has also authored articles on Wealth Management, Wealth Preservation and need for Estate Planning for investors. Deepak is MBA in Finance & Marketing and holds Bachelor's degree in Computer Science from Pune University.
 Mr. Sanjib Parhi
Sanjib has over 30 years of experience, building retail distribution in insurance, financial services, institutional sales and managing wealth for HNIs. Worked in various organisations like HDFC Life, Financial Technologies, Motorola (Page Point), Ion Exchange and Timeshare industry. His last assignment was with HDFC Life as an Associate Vice President where he worked for 15 years in managing retail agency distribution. Sanjib has done his management (DMM) from NMIMS Mumbai University.


Build a retirement corpus with a low-cost, PFRDA-regulated pension account. Choose how your money is invested across equity, corporate debt and government securities, and keep the same account across jobs and cities.
Check or complete your KYC using your PAN
Aadhaar (masked) and bank proof
Sign your forms digitally with an OTP
Invest through the app or your RM
The National Pension System (NPS) is a voluntary, long-term retirement savings scheme regulated by the Pension Fund Regulatory and Development Authority (PFRDA). It is market-linked and low-cost, and is open to salaried and self-employed individuals, professionals and NRIs (subject to FEMA rules) between 18 and 70 years of age.
Each subscriber gets a Permanent Retirement Account Number (PRAN), which stays with you across employers and locations.
| Tier I | Tier II | |
|---|---|---|
| Purpose | Primary retirement account | Optional, voluntary account |
| Lock-in | Till age 60 | No lock-in |
| Tax deduction | Yes (subject to tax regime) | No |
| Employer contribution benefit | Yes | No |
| Withdrawals | Partial, under set conditions | Flexible |
Equity and equity-related instruments, with higher return potential and higher volatility.
Corporate bonds and fixed income instruments, with a moderate risk and return profile.
Central and state government bonds, with a lower risk profile.
Limited exposure to instruments such as REITs and InvITs, within regulatory limits.
You set the mix across E, C, G and A. Equity can go up to 75%, with age-based caps.
Lifecycle funds (Aggressive, Moderate or Conservative) that reduce equity gradually as you age.
NPS investments are managed by PFRDA-registered Pension Fund Managers, including SBI Pension Funds, UTI Retirement Solutions, LIC Pension Fund, HDFC Pension Fund, ICICI Prudential Pension Fund, Kotak Pension Fund, Aditya Birla Sun Life Pension Fund, Axis Pension Fund, Tata Pension Management and Max Life Pension Fund.
Subscribers may choose and change fund managers as per prescribed rules.
Tax treatment depends on the type of contribution and the tax regime opted by the individual. Section 80CCD(2) is available under both Old and New Tax Regimes, which makes NPS particularly relevant for individuals opting for the New Tax Regime.
Keep these handy for a smooth start. We never ask for your full Aadhaar number; a masked copy is enough.
Talk to your relationship manager or start online in minutes.
NPS is a market-linked product regulated by PFRDA. Returns are not guaranteed. Tax benefits depend on your tax regime and prevailing law; please consult your tax adviser before investing.


