Download SATCO App
Track your portfolio on the go
 Bank Grade Security & Encryption
 Dedicated RM Support
 Industry Connect & Networking
 Regular Portfolio Monitoring
The people behind Satco Wealth.
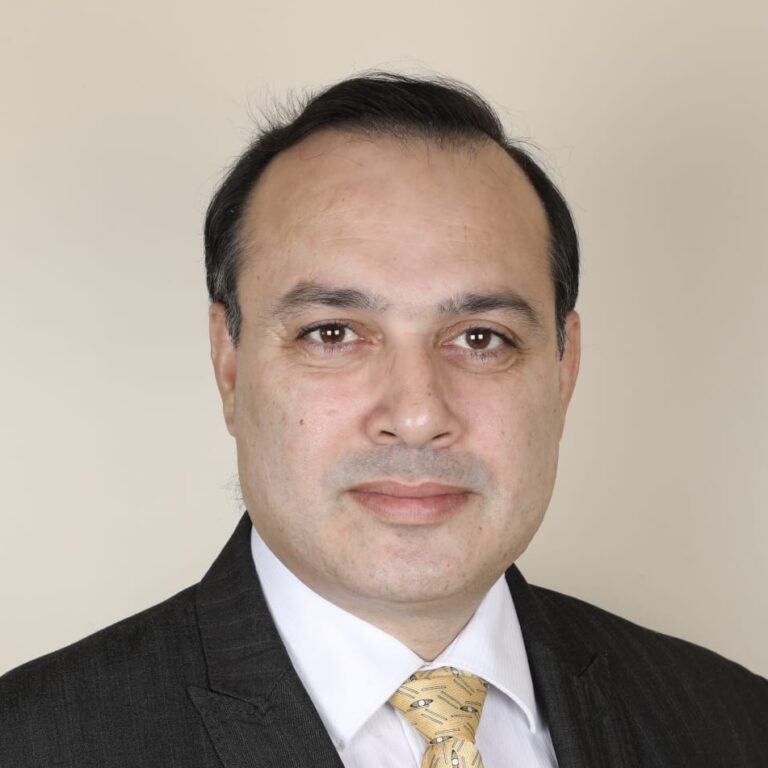 Mr. Deepak Jaggi
Deepak has over 30 years of experience in building retail businesses in financial services that has included his stint in Private Banking, Life Insurance, PMS and Mutual Funds. Worked in organizations like Kotak Securities, Zurich Mutual Fund, HDFC Life Insurance and Deutsche Mutual Fund. His last assignment was with PGIM Mutual Fund as an Executive Director and Head of Retail Sales pan India. He has also authored articles on Wealth Management, Wealth Preservation and need for Estate Planning for investors. Deepak is MBA in Finance & Marketing and holds Bachelor's degree in Computer Science from Pune University.
 Mr. Sanjib Parhi
Sanjib has over 30 years of experience, building retail distribution in insurance, financial services, institutional sales and managing wealth for HNIs. Worked in various organisations like HDFC Life, Financial Technologies, Motorola (Page Point), Ion Exchange and Timeshare industry. His last assignment was with HDFC Life as an Associate Vice President where he worked for 15 years in managing retail agency distribution. Sanjib has done his management (DMM) from NMIMS Mumbai University.


A plain-language summary of how income and investments are taxed in India for FY 2026-27, the first year under the new Income-tax Act, 2025. Use it to plan, and confirm your own position with a tax adviser.
Compare new and old for your income
If the old regime suits you better
Use the ₹1.25 lakh yearly LTCG exemption
Report gains and foreign assets correctly
The new regime is the default. Resident individuals with taxable income up to ₹12 lakh pay no tax because of the rebate, and salaried taxpayers also get a ₹75,000 standard deduction. A 4% health and education cess applies on the tax.
| Taxable income | Tax rate |
|---|---|
| Up to ₹4 lakh | Nil |
| ₹4 lakh – ₹8 lakh | 5% |
| ₹8 lakh – ₹12 lakh | 10% |
| ₹12 lakh – ₹16 lakh | 15% |
| ₹16 lakh – ₹20 lakh | 20% |
| ₹20 lakh – ₹24 lakh | 25% |
| Above ₹24 lakh | 30% |
| Investment | Short-term | Long-term |
|---|---|---|
| Listed equity & equity funds | 20%, if held up to 12 months | 12.5% on gains above ₹1.25 lakh a year |
| Debt funds bought after 1 April 2023 | Your slab rate | Your slab rate |
| FD and bond interest | Your slab rate | Your slab rate |
| Listed bonds and gold ETFs (on sale) | Slab rate, if held up to 12 months | 12.5% after 12 months |
| Mutual fund IDCW (dividends) | Your slab rate | Your slab rate |
ELSS, PPF, life insurance premiums and more, up to ₹1.5 lakh a year (formerly Section 80C).
Premiums for yourself, family and parents, within the prescribed limits (formerly Section 80D).
An extra deduction of up to ₹50,000 for your own NPS contributions (formerly Section 80CCD(1B)).
Interest on a self-occupied home, up to ₹2 lakh a year.
| Financial year | Tax regime | Download |
|---|---|---|
| FY 2020-21 | Old regime, with the new regime introduced as an option | |
| FY 2019-20 | Old regime | |
| FY 2018-19 | Old regime | |
| FY 2016-17 | Old regime | |
| FY 2015-16 | Old regime | |
| FY 2014-15 | Old regime | |
| FY 2013-14 | Old regime |
Archived guides reflect the rules of their year and are kept for reference only.
Talk to your relationship manager or start online in minutes.
This guide is general information based on rules applicable to FY 2026-27 and is not tax advice. Tax laws change; please consult a qualified tax professional.


