Download SATCO App
Track your portfolio on the go
 Bank Grade Security & Encryption
 Dedicated RM Support
 Industry Connect & Networking
 Regular Portfolio Monitoring
The people behind Satco Wealth.
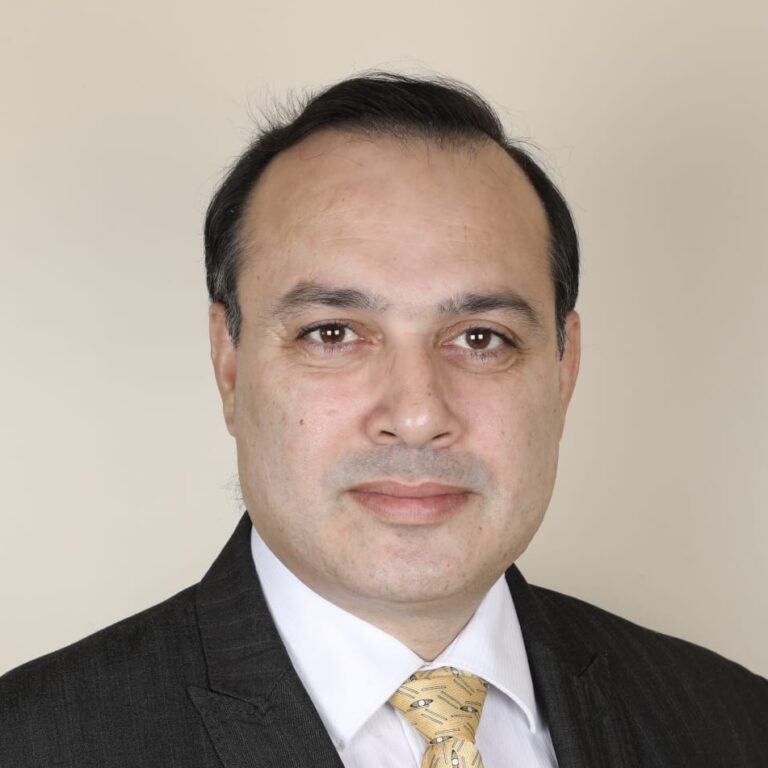 Mr. Deepak Jaggi
Deepak has over 30 years of experience in building retail businesses in financial services that has included his stint in Private Banking, Life Insurance, PMS and Mutual Funds. Worked in organizations like Kotak Securities, Zurich Mutual Fund, HDFC Life Insurance and Deutsche Mutual Fund. His last assignment was with PGIM Mutual Fund as an Executive Director and Head of Retail Sales pan India. He has also authored articles on Wealth Management, Wealth Preservation and need for Estate Planning for investors. Deepak is MBA in Finance & Marketing and holds Bachelor's degree in Computer Science from Pune University.
 Mr. Sanjib Parhi
Sanjib has over 30 years of experience, building retail distribution in insurance, financial services, institutional sales and managing wealth for HNIs. Worked in various organisations like HDFC Life, Financial Technologies, Motorola (Page Point), Ion Exchange and Timeshare industry. His last assignment was with HDFC Life as an Associate Vice President where he worked for 15 years in managing retail agency distribution. Sanjib has done his management (DMM) from NMIMS Mumbai University.


Rising medical costs can undo years of savings. Understand the types of health cover, from base policies to super top-ups, and the features that matter most when you compare plans.
Work out the cover you and your family need
Spot gaps in the policies you already hold
Know what to check before you buy
From an IRDAI-licensed insurer or intermediary
A separate sum insured for each person.
One sum insured shared by the whole family, usually cheaper than separate covers.
Designed for parents above 60, with suitable entry ages and co-payment options.
Extra cover that starts after a deductible: a low-cost way to raise your total cover.
A lump sum on diagnosis of listed serious illnesses, regardless of hospital bills.
Talk to your relationship manager or start online in minutes.
This page is for information only. Satco Wealth is not an insurance intermediary and does not sell or service insurance policies; please buy directly from an IRDAI-licensed insurer or intermediary.


